
Video game publisher Take Two (NASDAQ:TTWO) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q2 2027), with revenue falling 23.6% year on year to $1.5 billion. Next quarter’s revenue guidance of $3.35 billion underwhelmed, coming in 3.7% below analysts’ consensus estimates. Its GAAP loss of $0.29 per share was 66.4% above analysts’ consensus estimates.
For more on Take-Two, read our free full research report.
Take-Two (TTWO) Q3 CY2026 highlights:
- Revenue $1.5 billion vs S&P analysts' consensus estimates of $1.65 billion (23.6% year-on-year decline, 9.5% miss)
- EPS (GAAP) -$0.29 vs analysts' consensus estimates of -$0.86 (66.4% beat)
- Adjusted EBITDA $92.2 million vs analysts' consensus estimates of $257.8 million (6.2% margin, 64.2% miss)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $8.08 billion at the midpoint from $8 billion
- GAAP EPS guidance $0.66 at the midpoint for the full year, missing analysts' consensus estimates by 61.6%
- EBITDA guidance $1.05 billion at the midpoint for the full year, below analysts' consensus estimates of $1.75 billion
- Operating margin -7.8%, down from -5% in the same quarter last year
- Free cash flow -$143 million compared to -$193.8 million in the previous quarter
- Market capitalization $40.18 billion
Strauss Zelnick, Chairman and CEO of Take-Two Interactive, stated: “The launch of Grand Theft Auto VI is ten days away and, with pre-orders continuing to reach unprecedented levels, we expect to deliver an historic year for our company. We are reiterating our outlook for Fiscal 2027 Net Bookings of $8 to $8.2 billion, and are confident in our ability to build on this incredible year as we release new hits, explore emerging business opportunities, expand our geographic footprint, and pursue accretive M&A – all of which will set us on a path to unlock greater earnings power and long-term shareholder value.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Take-Two’s revenue grew at a sluggish 4.7% compounded annual growth rate over the last three years. That was an underwhelming result compared to the rest of the consumer internet sector, but there are still things to like about Take-Two.
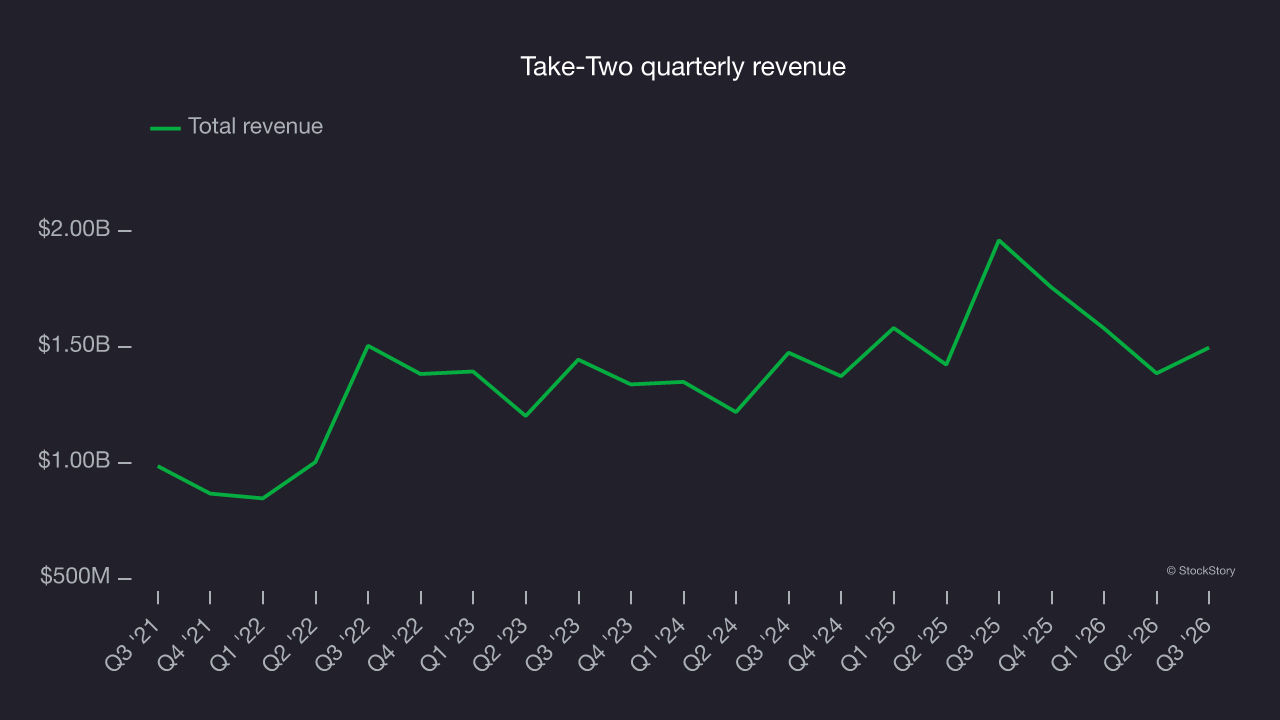
This quarter, Take-Two missed Wall Street’s consensus estimates and reported an uninspiring 23.6% year-on-year revenue decline, generating $1.5 billion of revenue. Management is guiding for a 90.4% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 59.3% over the next 12 months, according to S&P, an acceleration versus the last three years. This strong projection indicates its newer products and services will drive better revenue performance.
Free cash flow
Free cash flow matters because accounting profits alone can’t pay the bills.
Take-Two has shown mediocre cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 2.4%, below expectations for a consumer internet business. The divergence from its good EBITDA margin stems from its capital-intensive business model, which requires Take-Two to make large cash investments in working capital (i.e., stocking inventories) and capex (i.e., building new facilities).
On the positive side, Take-Two’s margin expanded by 6.2 percentage points over the last few years. That improvement shows it’s heading in the right direction, and the rise in free cash flow profitability alongside falling operating profitability indicates it became a less capital-intensive business.
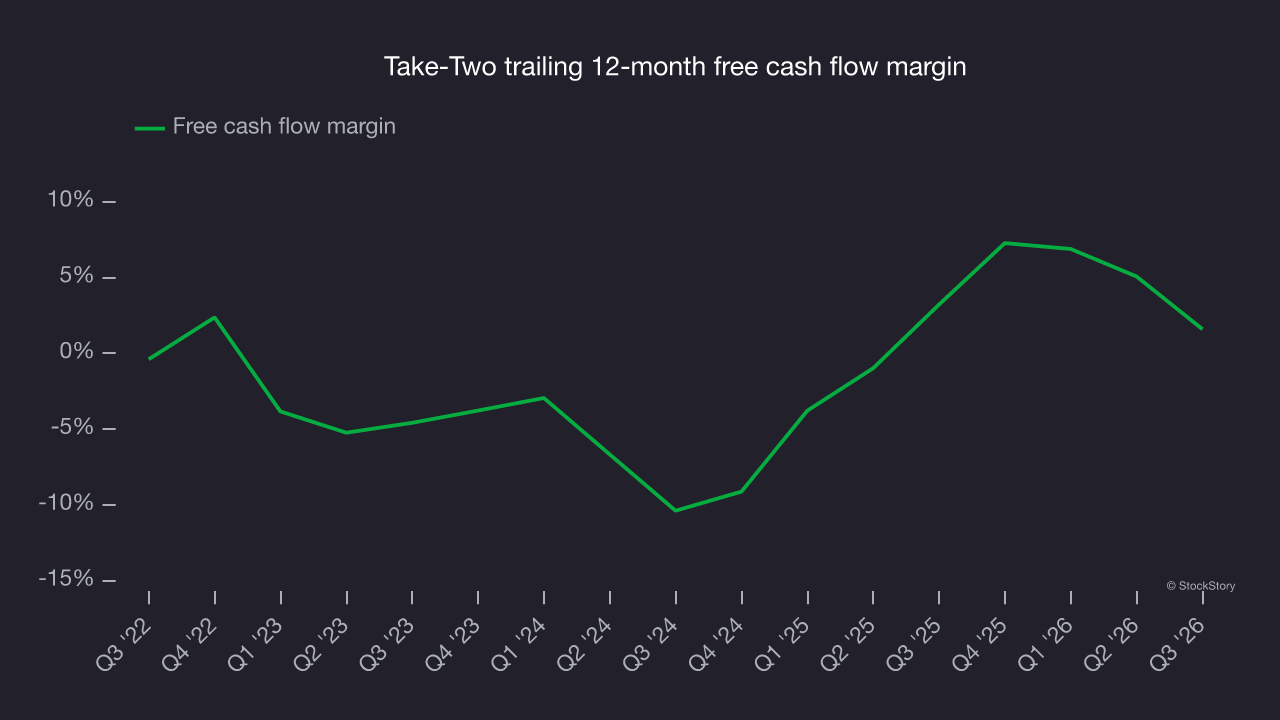
Take-Two used $143 million of cash in Q3, equivalent to a negative 9.6% margin. The company’s cash flow turned negative after being positive in the same quarter last year, but that short-term change warrants caution because investment needs can be seasonal, leading to temporary swings. Long-term trends carry greater meaning.
Key takeaways from Take-Two’s Q3 results
Take-Two’s weaker quarter offered few positives. Its full-year outlook disappointed on both fronts: revenue guidance missed expectations, and EBITDA guidance fell short of Wall Street’s consensus estimates. Shares rose 2.9% to $215.65 immediately after the results.
How should investors assess Take-Two? When making that decision, it’s important to consider its valuation, business quality and latest quarterly results. For more on Take-Two, read the full research report here (it’s free).