
Real estate brokerage and services firm Marcus & Millichap (NYSE:MMI) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 7.5% year on year to $208.4 million. Its GAAP profit of $0.03 per share was 53.8% below analysts’ consensus estimates.
For more on Marcus & Millichap, read our free full research report.
Marcus & Millichap (MMI) Q3 2026 highlights:
- Revenue $208.4 million vs S&P analysts’ consensus estimates of $205.1 million (7.5% year-on-year growth, 1.6% beat)
- EPS (GAAP) $0.03 vs analysts’ consensus estimates of $0.07 (53.8% miss)
- Adjusted EBITDA $8.24 million vs analysts’ consensus estimates of $3.5 million (4% margin, significant beat)
- Operating margin -0.4%, in line with the same quarter last year
- Market capitalization $1.09 billion
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Marcus & Millichap struggled to consistently generate demand over the last five years as its revenue dropped at a 4.7% annual rate. That underwhelming result suggests it is a low-quality business.
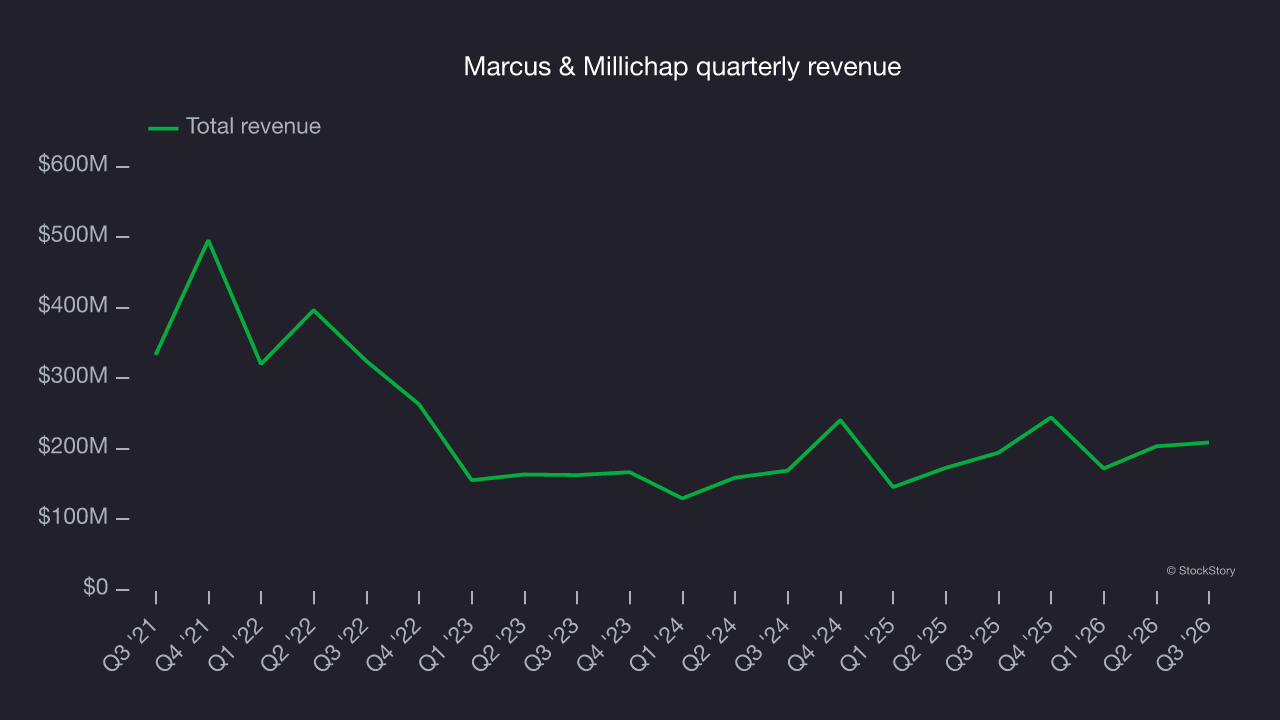
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. Marcus & Millichap’s annualized revenue growth of 15.3% over the last two years is above its five-year trend, a positive sign. 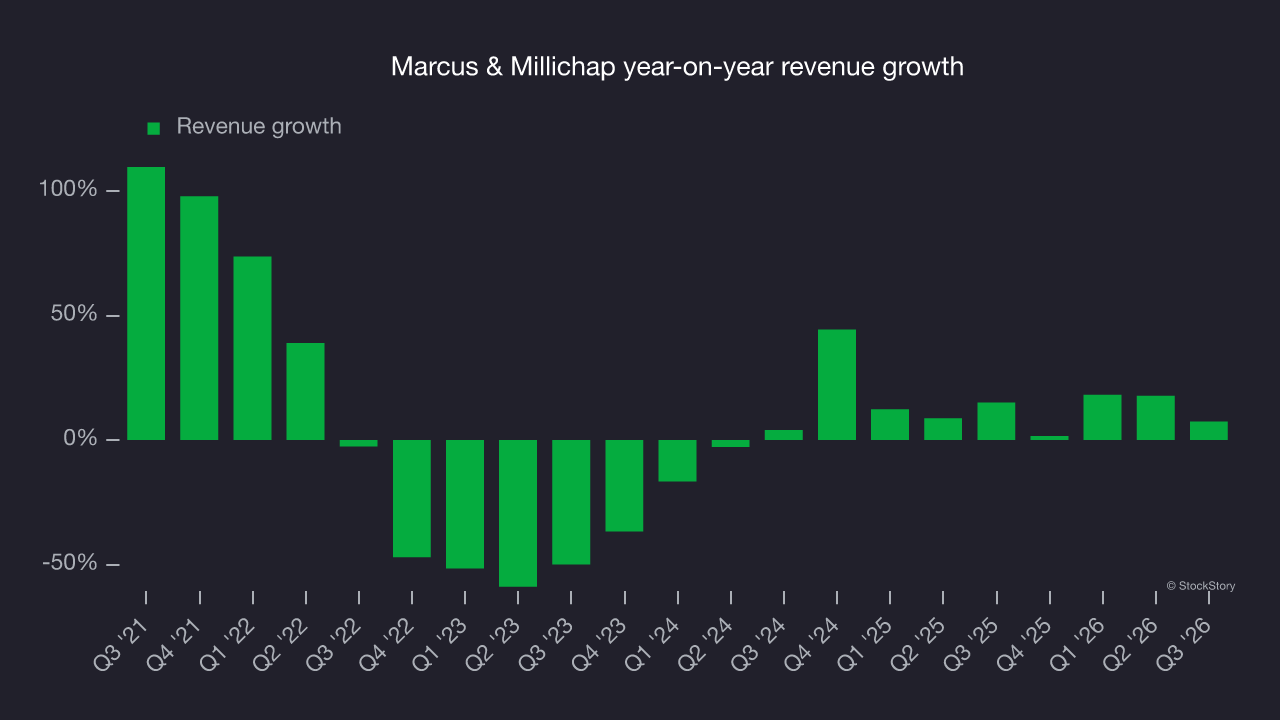
We can better understand the company’s revenue dynamics by analyzing its most important segments, Brokerage and Financing, which are 83.6% and 12.9% of revenue. Over the last two years, Marcus & Millichap’s Brokerage revenue (commission fees) averaged 10% year-on-year growth while its Financing revenue (financing fees) averaged 24.2% growth. 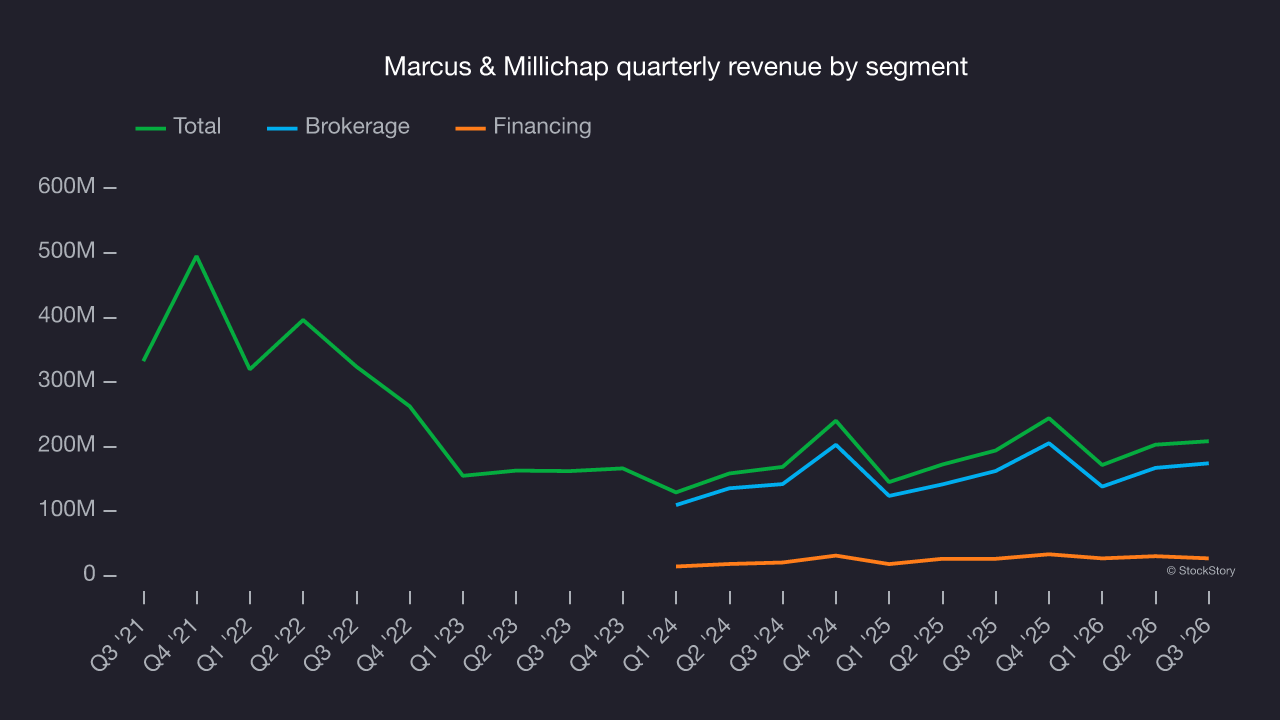
This quarter, Marcus & Millichap reported year-on-year revenue growth of 7.5%, and its $208.4 million of revenue exceeded Wall Street’s consensus estimates by 1.6%.
Looking ahead, sell-side analysts expect revenue to grow 7.8% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will see some demand headwinds.
Operating margin
Marcus & Millichap’s operating margin has risen over the last 12 months, leading to break-even profits over the last two years. However, its large expense base and inefficient cost structure mean it still has inadequate profitability for a consumer discretionary business.
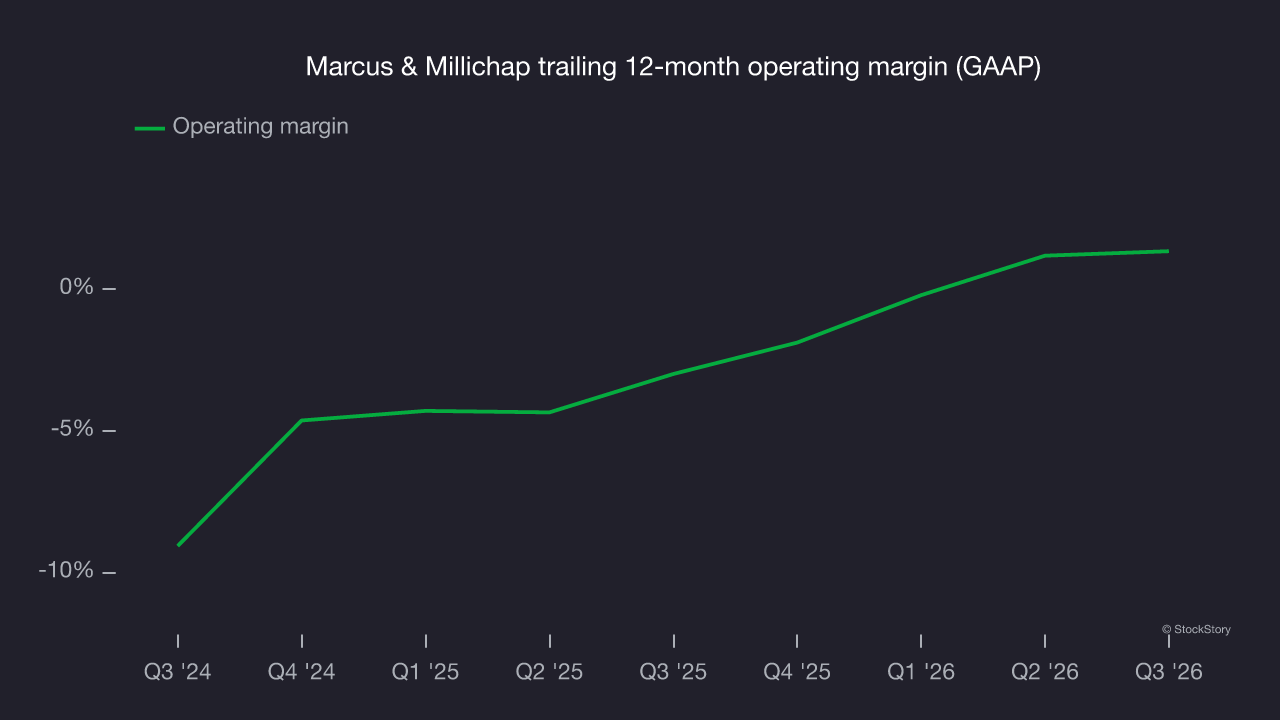
In Q3, Marcus & Millichap generated a negative 0.4% operating margin. The company’s consistent lack of profits is a concern.
Earnings per share
Long-term changes in earnings per share, or EPS, matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Marcus & Millichap’s EPS declined by 31.5% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
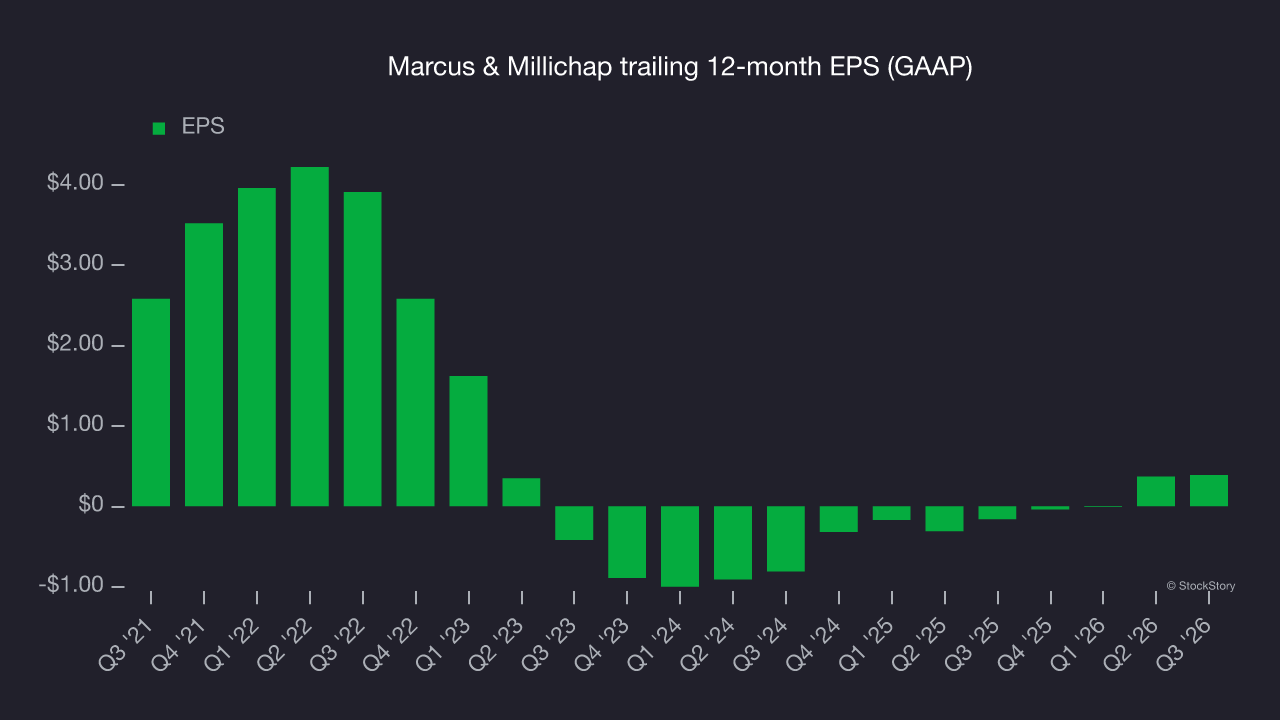
In Q3, Marcus & Millichap reported EPS of $0.03, up from $0.01 in the same quarter last year. Despite growing year on year, EPS missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Marcus & Millichap’s full-year EPS to grow 55.1% from $0.39 to $0.61, according to S&P.
Key takeaways from Marcus & Millichap’s Q3 results
Marcus & Millichap’s Q3 results were mixed: EBITDA beat analysts’ consensus estimates by a wide margin and revenue topped Wall Street’s consensus, but EPS missed. Shares remained flat at $28.66 immediately after the results.
For investors considering Marcus & Millichap, the latest quarter is only one part of assessing longer-term business quality. Quality, when combined with valuation, can help determine if the stock is a buy. Read the full research report here (it’s free).