
Tobacco company Philip Morris International (NYSE:PM) reported Q3 2026 results beating Wall Street’s revenue expectations, with sales up 5.5% year on year to $11.44 billion. Its non-GAAP profit of $2.36 per share was 1.9% above analysts’ consensus estimates.
Is now the time to buy Philip Morris? Find out by accessing our full research report, it’s free.
Philip Morris (PM) Q3 2026 highlights:
- Revenue: $11.44 billion vs analyst estimates of $11.32 billion (5.5% year-on-year growth, 1% beat)
- Adjusted EPS: $2.36 vs analyst estimates of $2.32 (1.9% beat)
- Operating Margin: 42.5%, up from 39.3% in the same quarter last year
- Market Capitalization: $311.6 billion
Company overview
Founded in 1847, Philip Morris International (NYSE:PM) manufactures and sells a wide range of tobacco and nicotine-containing products, including cigarettes, heated tobacco products, and oral nicotine pouches.
Revenue growth
Reviewing a company’s long-term sales performance reveals insights into its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years.
With $43.14 billion in revenue over the past 12 months, Philip Morris is one of the most widely recognized consumer staples companies. Its influence over consumers gives it negotiating leverage with distributors, enabling it to pick and choose where it sells its products (a luxury many don’t have).
As you can see below, Philip Morris’s 8% annualized revenue growth over the last three years was decent. This shows its offerings generated slightly more demand than the average consumer staples company, a helpful starting point for our analysis.
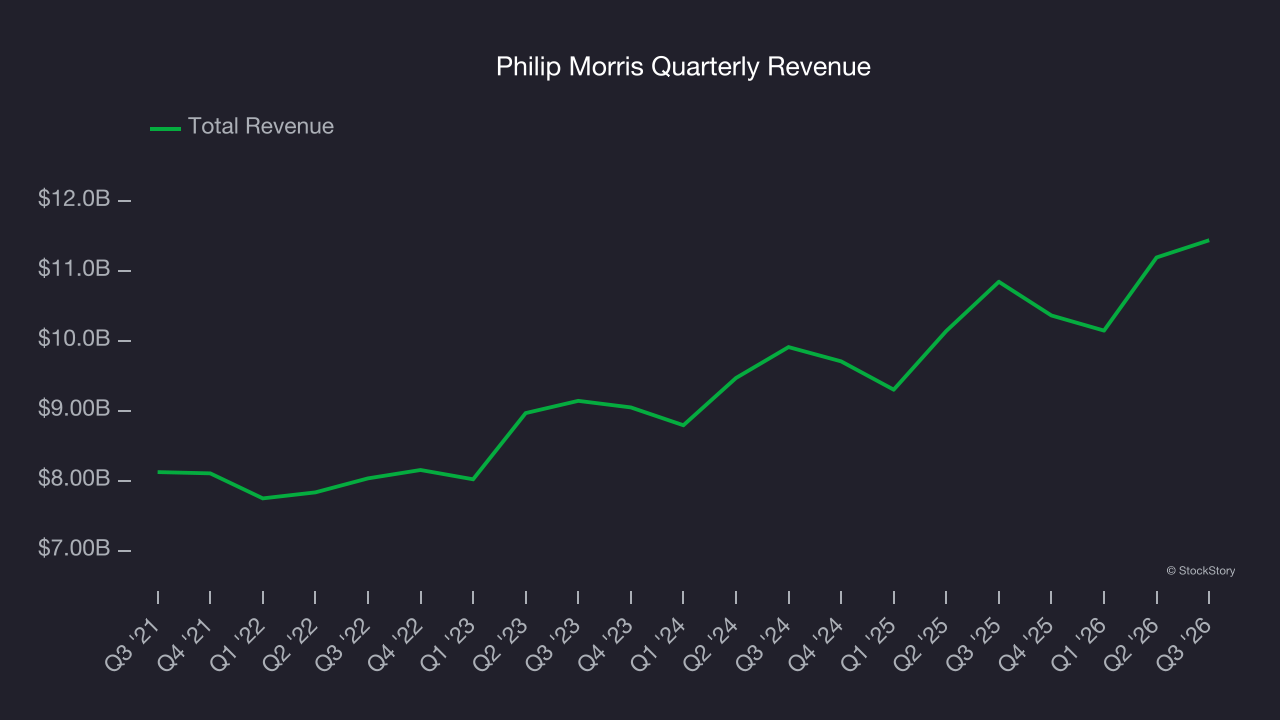
This quarter, Philip Morris reported year-on-year revenue growth of 5.5%, and its $11.44 billion of revenue exceeded Wall Street’s estimates by 1%.
Looking ahead, sell-side analysts expect revenue to grow 5.1% over the next 12 months, a slight deceleration versus the last three years. We still think its growth trajectory is satisfactory given its scale and indicates the market is forecasting success for its products.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Cash is king
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
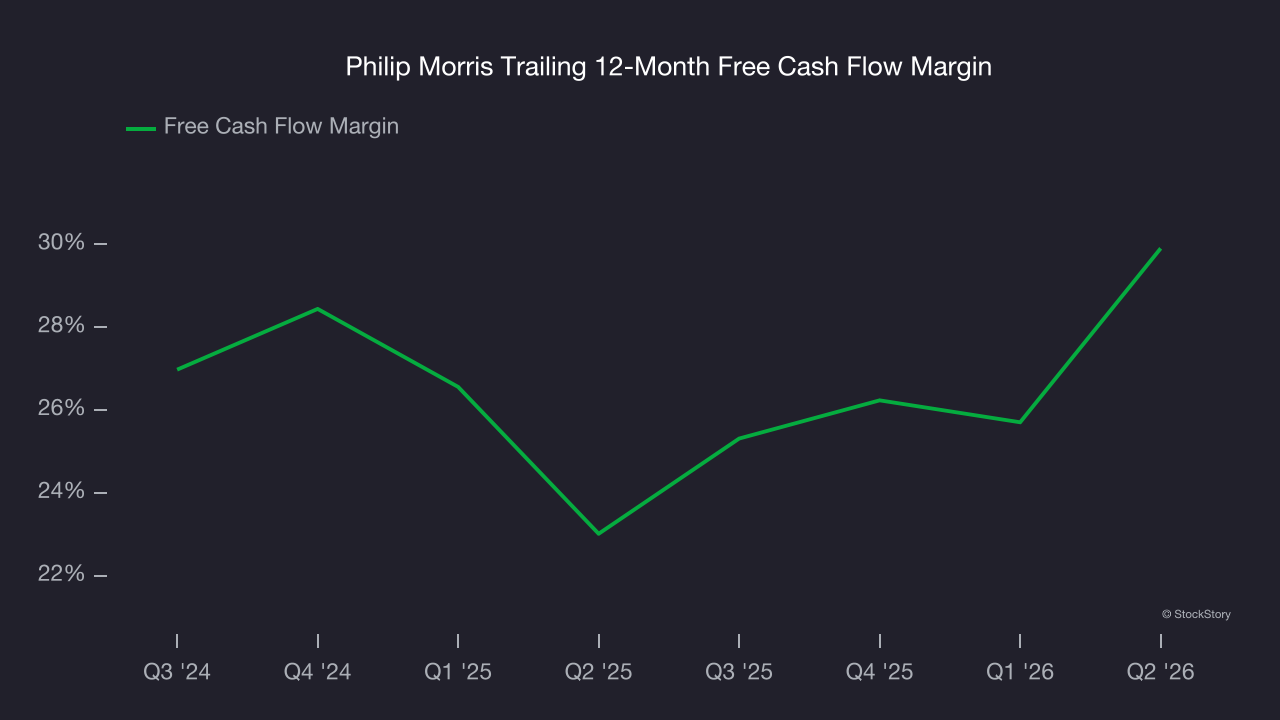
Philip Morris has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the consumer staples sector, averaging 26.2% over the last two years.
Key takeaways from Philip Morris’s Q3 results
It was good to see Philip Morris narrowly top analysts’ revenue expectations this quarter. Zooming out, we think this was a decent quarter. Investors were likely hoping for more, and shares traded down 3.4% to $193.19 immediately after reporting.
Should you buy the stock or not? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).